Hypothesis: Extreme positive funding rates predict short-term mean reversion
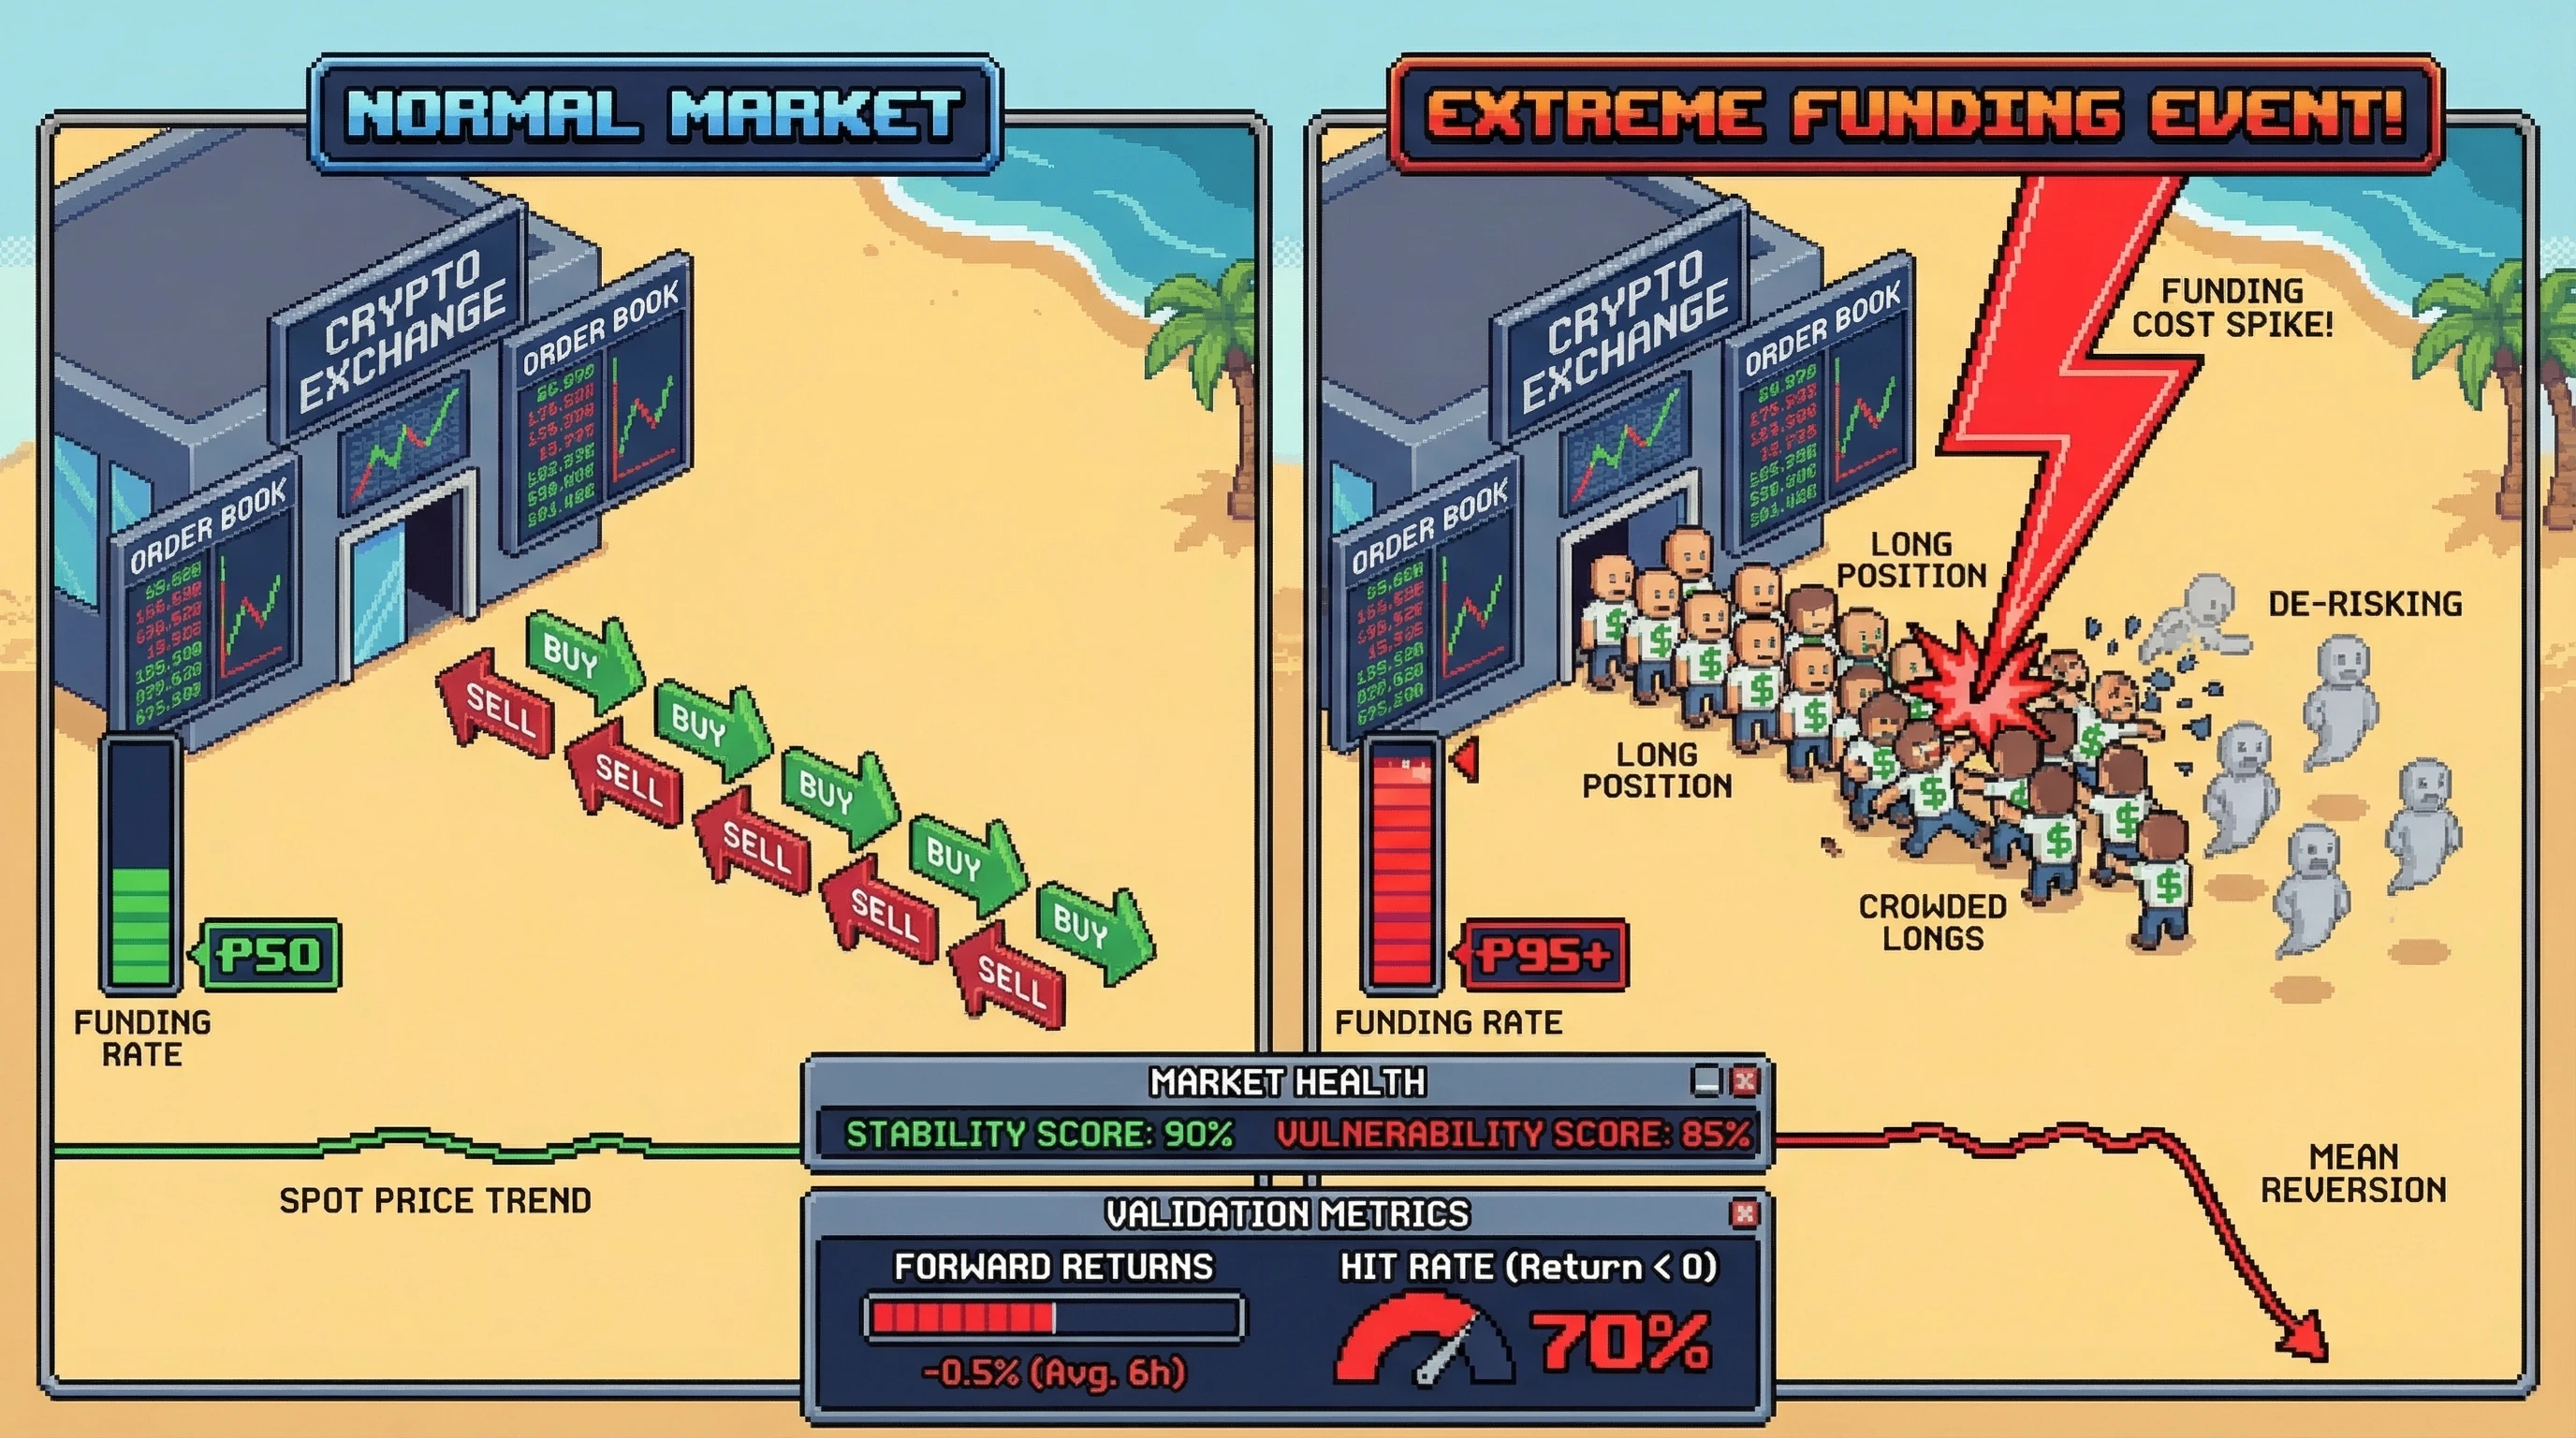
Claim: When perp funding rate is in the extreme positive tail (e.g., top 1–5% of its 30–90d distribution), the next 6–12 hours of spot returns are negative on average (mean reversion).
Rationale: Extreme positive funding indicates overcrowded long positioning. As funding cost spikes, marginal longs de-risk, and short-term liquidity becomes one-sided, increasing vulnerability to squeeze/reversal.
Test:
- Define extreme funding as funding rate > P95 (or P99) of trailing 90d for each market.
- For each extreme event, compute forward spot returns at +6h and +12h.
- Compare to baseline unconditional returns and to non-extreme periods.
Metrics:
- Mean forward return (t-test / bootstrap CI)
- Hit rate (P[return < 0])
- Effect size vs. baseline
Falsifier: If forward returns are not significantly negative (or are positive) after extreme funding spikes, the hypothesis fails.
Notes: Control for volatility regime and major news events to avoid confounding.